

I originally planned to write a full Deep-Dive on InPost. But with the recent takeover offer, the setup has shifted from a classic compounder story to a more event-driven situation with the long-term upside being capped for long-term investors (sadly).
There is still a small chance another buyer steps in and emerges with a higher bid. On the other side, the current bid might not be successful if the minimum acceptance threshold of 80% is not reached, as the consortium is lowballing long-term investors with a shamelessly low bid.
It is a disgrace to confidence in the capital markets when an opportunistic offer that exploits short-term price weakness allows a company to be stolen from minority shareholders.
Given this situation, an 80-page report would now be overkill in parts. What remains extremely relevant, however, is the business model. It’s always fun to analyze great and extremely successful companies. It trains our sense of pattern recognition.
If you want to understand InPost, you need to understand why a dense network of parcel lockers (Automated Parcel Machines, or APMs) creates structural advantages for consumers, merchants, and InPost itself which allowed a revenue CAGR of 56% from 2017-2024 with ROIIC exceeding 50% (!) in Poland — and why that same logic can repeat outside Poland.
1. The core product: parcel lockers vs. doorstep delivery
InPost is a European last-mile logistics company whose network is built around out-of-home (OOH) delivery, as opposed to traditional to-door delivery to the customer’s home. Parcels are delivered either to parcel lockers (APMs) or to pick-up/drop-off points (PUDOs, such as kiosks, shops, or post offices). APMs are modular locker systems placed at high-traffic locations — supermarkets, commuting routes, residential complexes — typically outdoors and available 24/7. Customers collect parcels by scanning a QR code in the InPost app ecosystem. Returns are often label-less: the customer drops the item into an assigned compartment and InPost takes it from there.
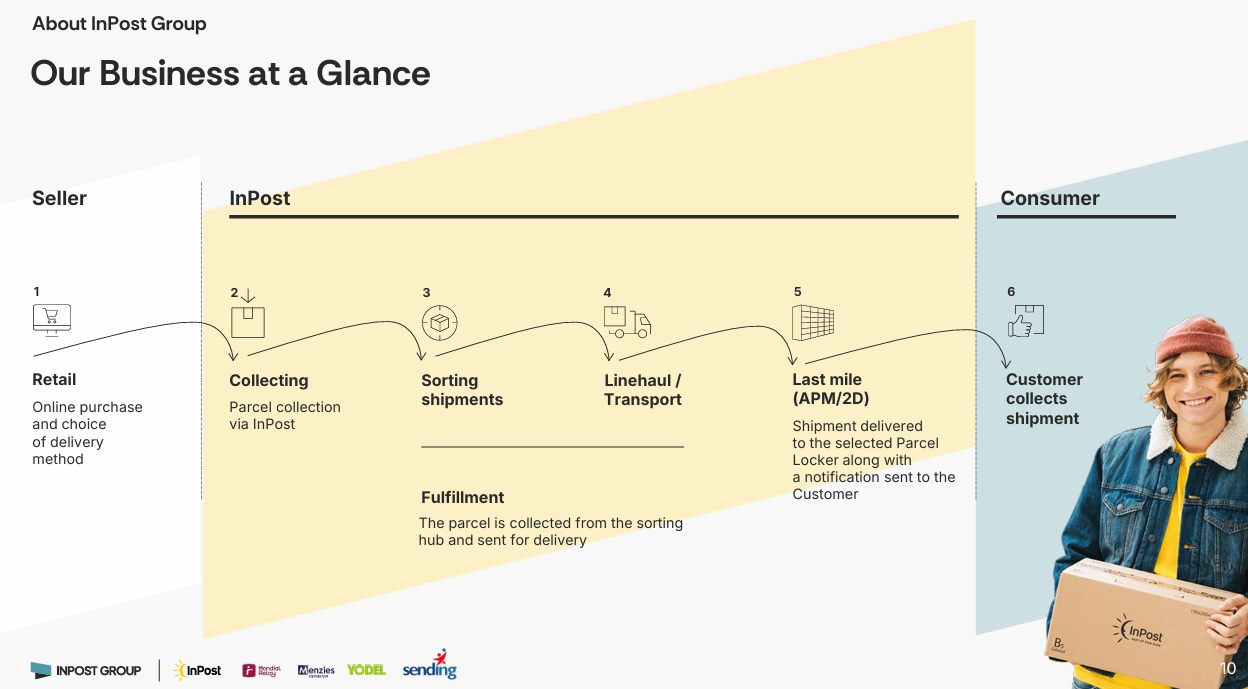
The graphic below summarizes InPost’s end-to-end parcel flow—from checkout to pickup—highlighting where the APM network sits in the value chain.
This seemingly small shift — the customers handling the last mile delivery themselves — changes the unit economics of delivery in a fundamental way. In a classic doorstep model, a driver typically delivers roughly 100 parcels per day (with only a few parcels per stop). With APM delivery, one stop at a well-utilized locker can mean unloading 50-150 parcels at once. With 7–10 APM stops per day, that can translate into up to ~1,000 parcels per driver per day. At sufficient utilization, this is where the structural cost advantage for a carrier like InPost comes from, as that cost advantage shows up as meaningfully lower shipping costs (paid by either the merchant or the end customer), which is the core reason APM delivery is so attractive.
A quick add-on: a PUDO driver can deliver ~500 parcels per day, because PUDOs don’t have the same capacity as APMs (in Poland, an APM averages up to ~145 compartments/lockers). In a PUDO model, the carrier saves on rent but pays a fee to the shop that operates the PUDO point. From the customer’s perspective, APMs tend to be more convenient than PUDOs because PUDOs have opening hours and the pick-up experience is usually less stringent and efficient than at an APM, whereas APMs are usually open 24/7 and do have a much shorter dwell time. In a PUDO, the customer might end up waiting in a queue for a few minutes and then waits again until the employee finds the package among 100 other packages. Unlike PUDOs, APMs deliver a uniform service level—so the customer experience is predictable—whereas PUDOs are only as good as the individual location. For that reason, from a customer experience and financial standpoint perspective, InPost prioritizes APM rollout much more than PUDO expansion.
You can think of the model as infrastructure. As a first mover, InPost secures the best locations for APM placement and then tries to drive high utilization across the network through service quality — which in turn benefits customers because it enables more locations. This flywheel tends to favor the first mover versus late entrants that start building an APM network years later and have to compete against an established market leader (where the best spots might be taken already by the first mover, i.e. InPost in Poland).
But it’s not a pure infrastructure play. The locker itself is just the hardware; the moat depends on service levels, reliability, customer support, seamless app UX, and—crucially—merchant acceptance. New entrants often place APMs right next to InPost lockers, yet run materially lower utilization, because customers and merchants default to the network they trust and that “just works” day in, day out.
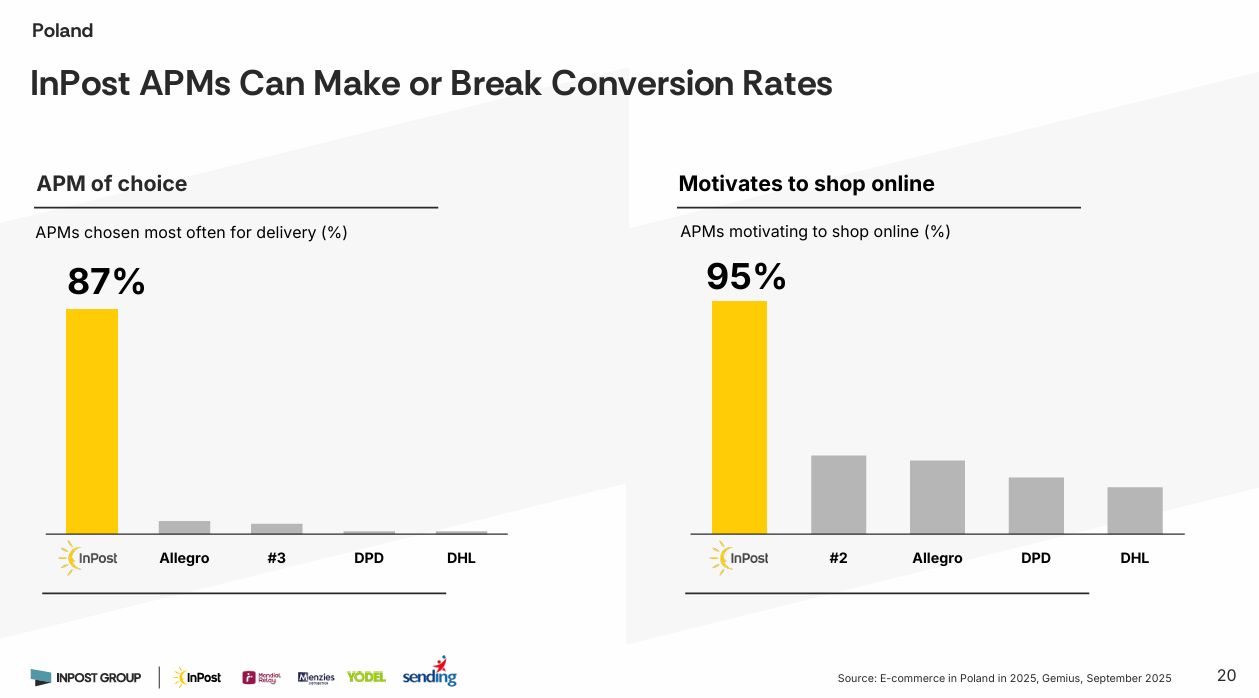
According to the following chart, InPost is THE preferred choice in Poland.
To be competitive, a network needs sufficient density to be attractive to the entire ecosystem: customers need lockers within easy walking distance, merchants need broad population coverage, and the operator needs to run the network profitably.
That creates the classic chicken-and-egg problem. A new independent entrant needs a network to win volumes and fill its lockers — but to win volumes, it first needs a network. Ramping up can take years, costs a lot of money (capex), and comes with accumulated losses from underutilization along the way.
2. Why APMs are a “win-win-win-win”
The APM model isn’t just cheaper to operate; it’s also more attractive for multiple stakeholders at the same time. That helps explain why adoption in Poland is so high and why InPost is gaining traction quickly in other countries.
2.1 Benefits for customers
For many customers, OOH is not a second-best option; it’s the preferred one. Parcel lockers are accessible around the clock, customers don’t have to wait at home for delivery windows (sometimes for multiple parcels from multiple carriers at different times), and pick-up can be integrated into existing routines (grocery shopping, commuting, fueling up, and so on). Failed deliveries are essentially eliminated, since there’s almost always capacity in the selected locker or at a nearby location. Theft risk is lower than leaving parcels at the doorstep, and pick-up often takes only a few seconds. There is also a habit and network effect: if you use the same lockers every day and the app is already on your phone, you have little incentive to switch systems for individual parcels.
2.2 Benefits for merchants
Merchants benefit in three ways: cost, reliability, and conversion. APM delivery typically costs about 20–30% less than doorstep delivery. At the same time, indirect costs decline because there are fewer failed deliveries, fewer re-delivery attempts, less damage, and fewer customer complaints. What matters even more (and is often underestimated): in markets with high InPost penetration, offering “InPost Locker” at checkout can noticeably increase conversion — some customers simply won’t order if they don’t see their preferred delivery option (in Germany, I think twice before ordering when I see GLS is handling delivery). This makes it unattractive for merchants to switch off InPost, even if a competitor temporarily tries to gain share with aggressive pricing. If you switch off InPost, your conversion might drop significantly.
2.3 Benefits for InPost
For InPost, the lever is productivity. More parcels per driver and per stop create operating leverage on the biggest cost buckets: labor and transportation. When the network reaches scale like in Poland, it allows InPost to earn an eyewatering ~50% EBITDA margin. Compare that to the 8.4% EBITDA margin DHL generated in the German Post & Parcel segment.
APMs are also modular. If demand grows, capacity can often be added at existing sites (assuming there is physical space) without having to secure an entirely new location.
2.4 Benefits for location partners
For location partners (supermarkets, transport companies, residential complexes), there’s an additional incentive: incremental rental income and higher foot traffic. Hosting the highest-utilization locker is the most attractive — a mechanism that tends to reinforce the leading platform.
3. The economics: why the model can support unusually high margins
Last-mile logistics is usually a low-margin business. Many traditional carriers end up somewhere in the 5–15% EBITDA margin range over time, even in mature markets with high market shares. InPost is an exception in Poland. The core driver is scale: a multi-layer network of depots, hubs, IT, fleet, and people comes with high fixed costs. Whoever wins volume and density can push the marginal cost per additional parcel down dramatically.
InPost can realize that scale effect faster than doorstep networks because APM delivery massively increases drop density. As a result, InPost can offer APM delivery 20–30% cheaper than incumbents’ doorstep delivery — and still remain above-average profitable. In its Polish core market, InPost already delivers more than 750 million parcels per year (over 600 million via APMs, with the rest to-door). That equates to roughly a ~50% market share: every second parcel in Poland is delivered by InPost. This scale enables an AEBITDA margin of ~50% in Poland (pre-lease) — a level that is rare in logistics.
In Poland, the company generated roughly ~PLN 2 billion of free cash flow (after leases) in 2025 on revenue of ~PLN 7 billion, implying an FCF margin of ~29%. If InPost were to stop investing in growth capex in Poland (with growth slowing), it could likely generate ~PLN 3 billion of FCF in 2026 almost immediately.
The twist is that efficiency gains are partly reinvested into lower prices and better service, which further increases penetration and accelerates the flywheel. We know “scale economies shared” from Amazon, Costco, and others — and we know the impact it can have on customer lifetime value. InPost lowered prices in Poland from ~PLN 9.1 per parcel (2018) to ~PLN 8.2 per parcel (2022), before inflation required an adjustment.
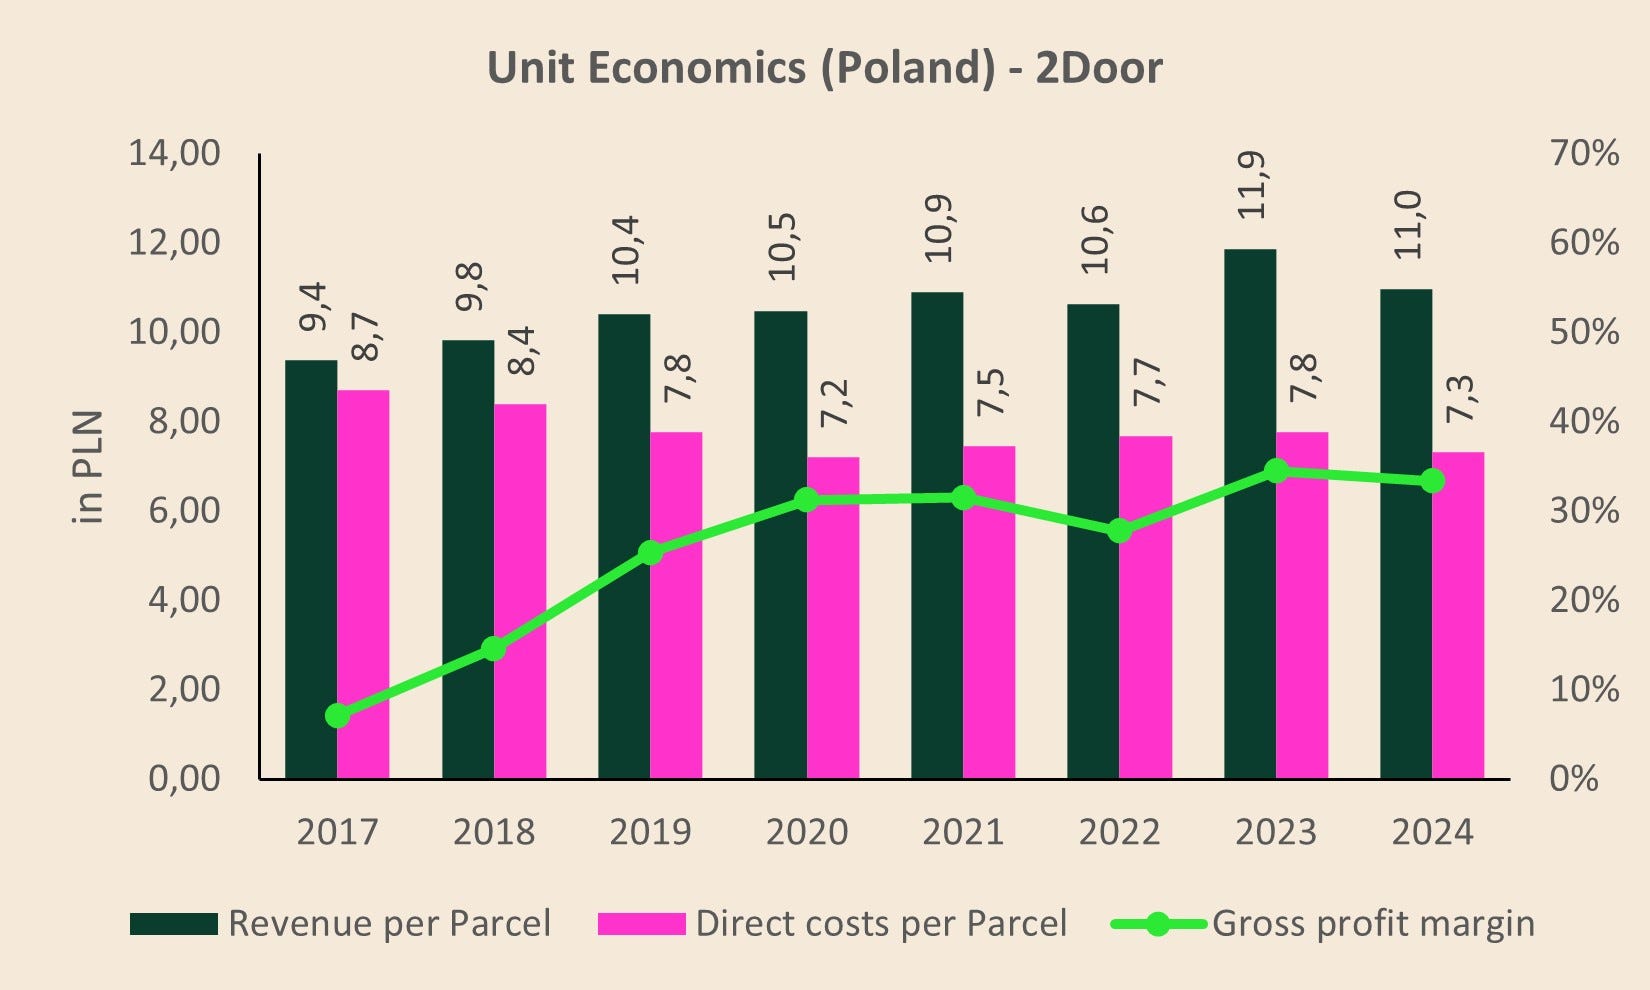
The two charts below make InPost’s operating leverage very tangible.
Compared to doorstep delivery (2Door), APM delivery comes with a lower price per parcel, but the direct cost per parcel drops even more. That’s the key: the last mile becomes a high-density “bulk drop,” so one stop can absorb dozens (or hundreds) of parcels instead of a handful of addresses.
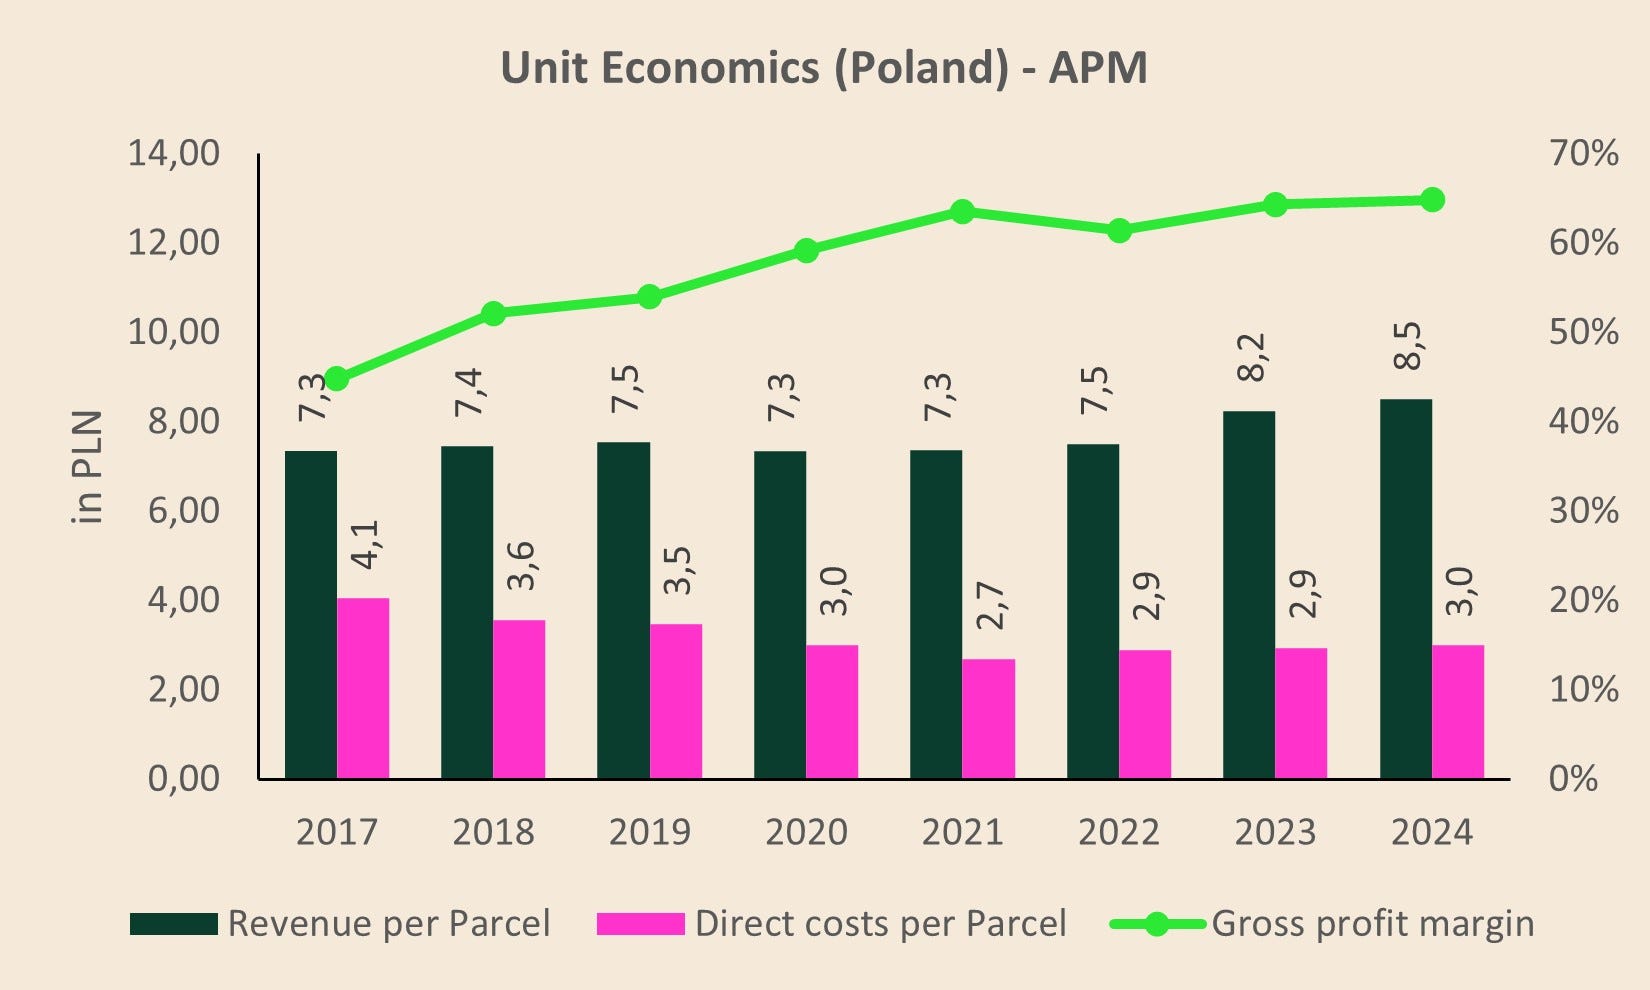
In 2Door, revenue per parcel is higher, but direct costs remain relatively elevated because the driver’s time and mileage scale with the number of individual drop-offs. With APMs, revenue per parcel is lower, yet direct costs per parcel are structurally lower thanks to much higher drop density (more parcels per stop, fewer stops per route, fewer failed deliveries and re-deliveries). The result is a materially higher gross margin per parcel in APMs and that margin expands as utilization rises.
4. Industry background & company history
Europe’s parcel market has been growing structurally for years, driven by e-commerce, higher delivery frequency, and a desire for faster, more reliable delivery options. At the same time, the “last mile” is the most expensive and operationally challenging part of the chain. Doorstep deliveries are labor-intensive, often fail on the first attempt, and create re-delivery costs, returns handling, and a meaningful CO2 footprint. That creates a clear economic incentive to bundle deliveries and standardize processes. This is exactly where OOH — especially APMs and PUDOs — come in: they make delivery more predictable, reduce cost per parcel, and improve the customer experience.
InPost is one of the pioneers of OOH delivery in Europe. The company built a dense parcel locker network early in Poland (first APM in 2009) and created an alternative delivery ecosystem with measurable benefits for both merchants and consumers. A key growth catalyst was tight integration with the Polish e-commerce ecosystem — especially high volumes linked to Allegro. The model worked particularly well in Poland because InPost achieved network effects early: as density increases, the system becomes more attractive for consumers (a locker closer by, higher availability), which attracts merchants and platforms; higher volumes improve utilization and lower unit costs, enabling further growth. It’s a flywheel in action.
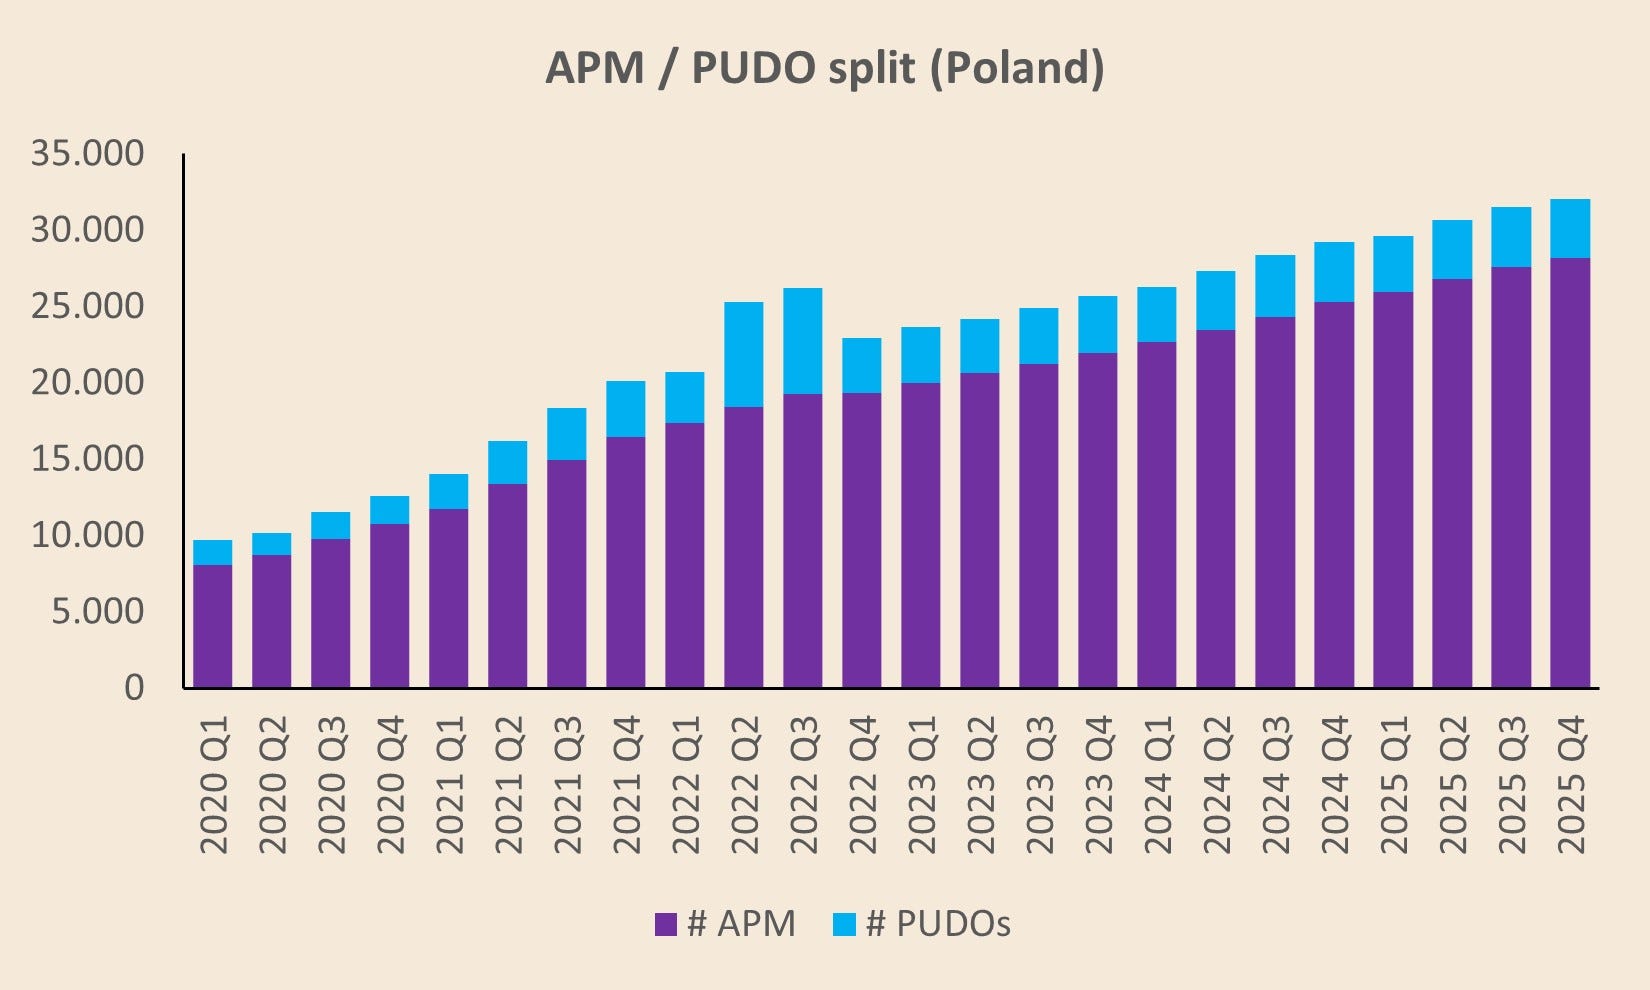
The chart below shows the development of InPost’s OOH locations in Poland. By the end of 2025, InPost had installed 28,165 APMs (installed capacity of 6.7 million compartments, or ~143 compartments per APM on average).
This Polish success story eventually moved InPost into the next phase: international expansion. Poland provided the proof of concept and the “cash engine,” while expansion into markets like France and the UK is meant to build a second leg of growth. The starting point is similar (high doorstep delivery costs, fragmented logistics landscapes, rising e-commerce penetration), but market dynamics differ: more competition, different consumer habits, different carrier structures — and therefore a longer ramp until density and utilization eventually reach Poland-like economics.
InPost already listed on the Warsaw stock exchange in 2015 to fund an initial internationalization push. But that push was too aggressive and the balance sheet became strained (also because there was no profitable core business yet to cross-fund expansion), which led to a take-private by private equity investor Advent in 2017 with a huge discount to the IPO price. Expansion plans were cut back significantly and later relaunched in a much more focused and disciplined way. Markets are “ready” for OOH today: parcel volumes are much higher than a decade ago and consumer acceptance of OOH solutions has increased.
5. Poland: Allegro as a growth turbo — and a stock risk
In Poland’s e-commerce ecosystem, Allegro plays a key role (think of it as “Poland’s Amazon”). After a major logistics contract in 2014, Allegro became a volume engine for InPost and the two businesses grew in tandem.
The mutual dependence is meaningful, but it has been reduced by InPost’s internationalization and a broader merchant base.
To understand the relationship, it helps to split it into two channels.
First, Allegro’s membership program “Smart!” (similar to Amazon Prime), where Allegro pays delivery costs for qualifying orders directly to the carrier (InPost). It’s covered by a framework between Allegro and InPost. Allegro guarantees a certain parcel volume to be channeled through the InPost network, while Allegro gets cheaper prices (vs. other merchants), while the prices are adjusted every year.
Second, “regular” Allegro orders outside Smart!, where merchants or customers pay for delivery and InPost often appears as an option at checkout — here, Allegro has less direct control over the carrier choice.
These symbiotic relationships are a double-edged sword. They can ignite a flywheel, but they also create concentration risk. That was one of the core reasons the stock struggled after the IPO. Allegro announced plans to build its own locker network, which the market interpreted as a potential attack on InPost’s moat. The result was a major de-rating — less because operations collapsed, and more because investors suddenly questioned whether the model was defensible and replicable. The stock experienced an ~80% drawdown.
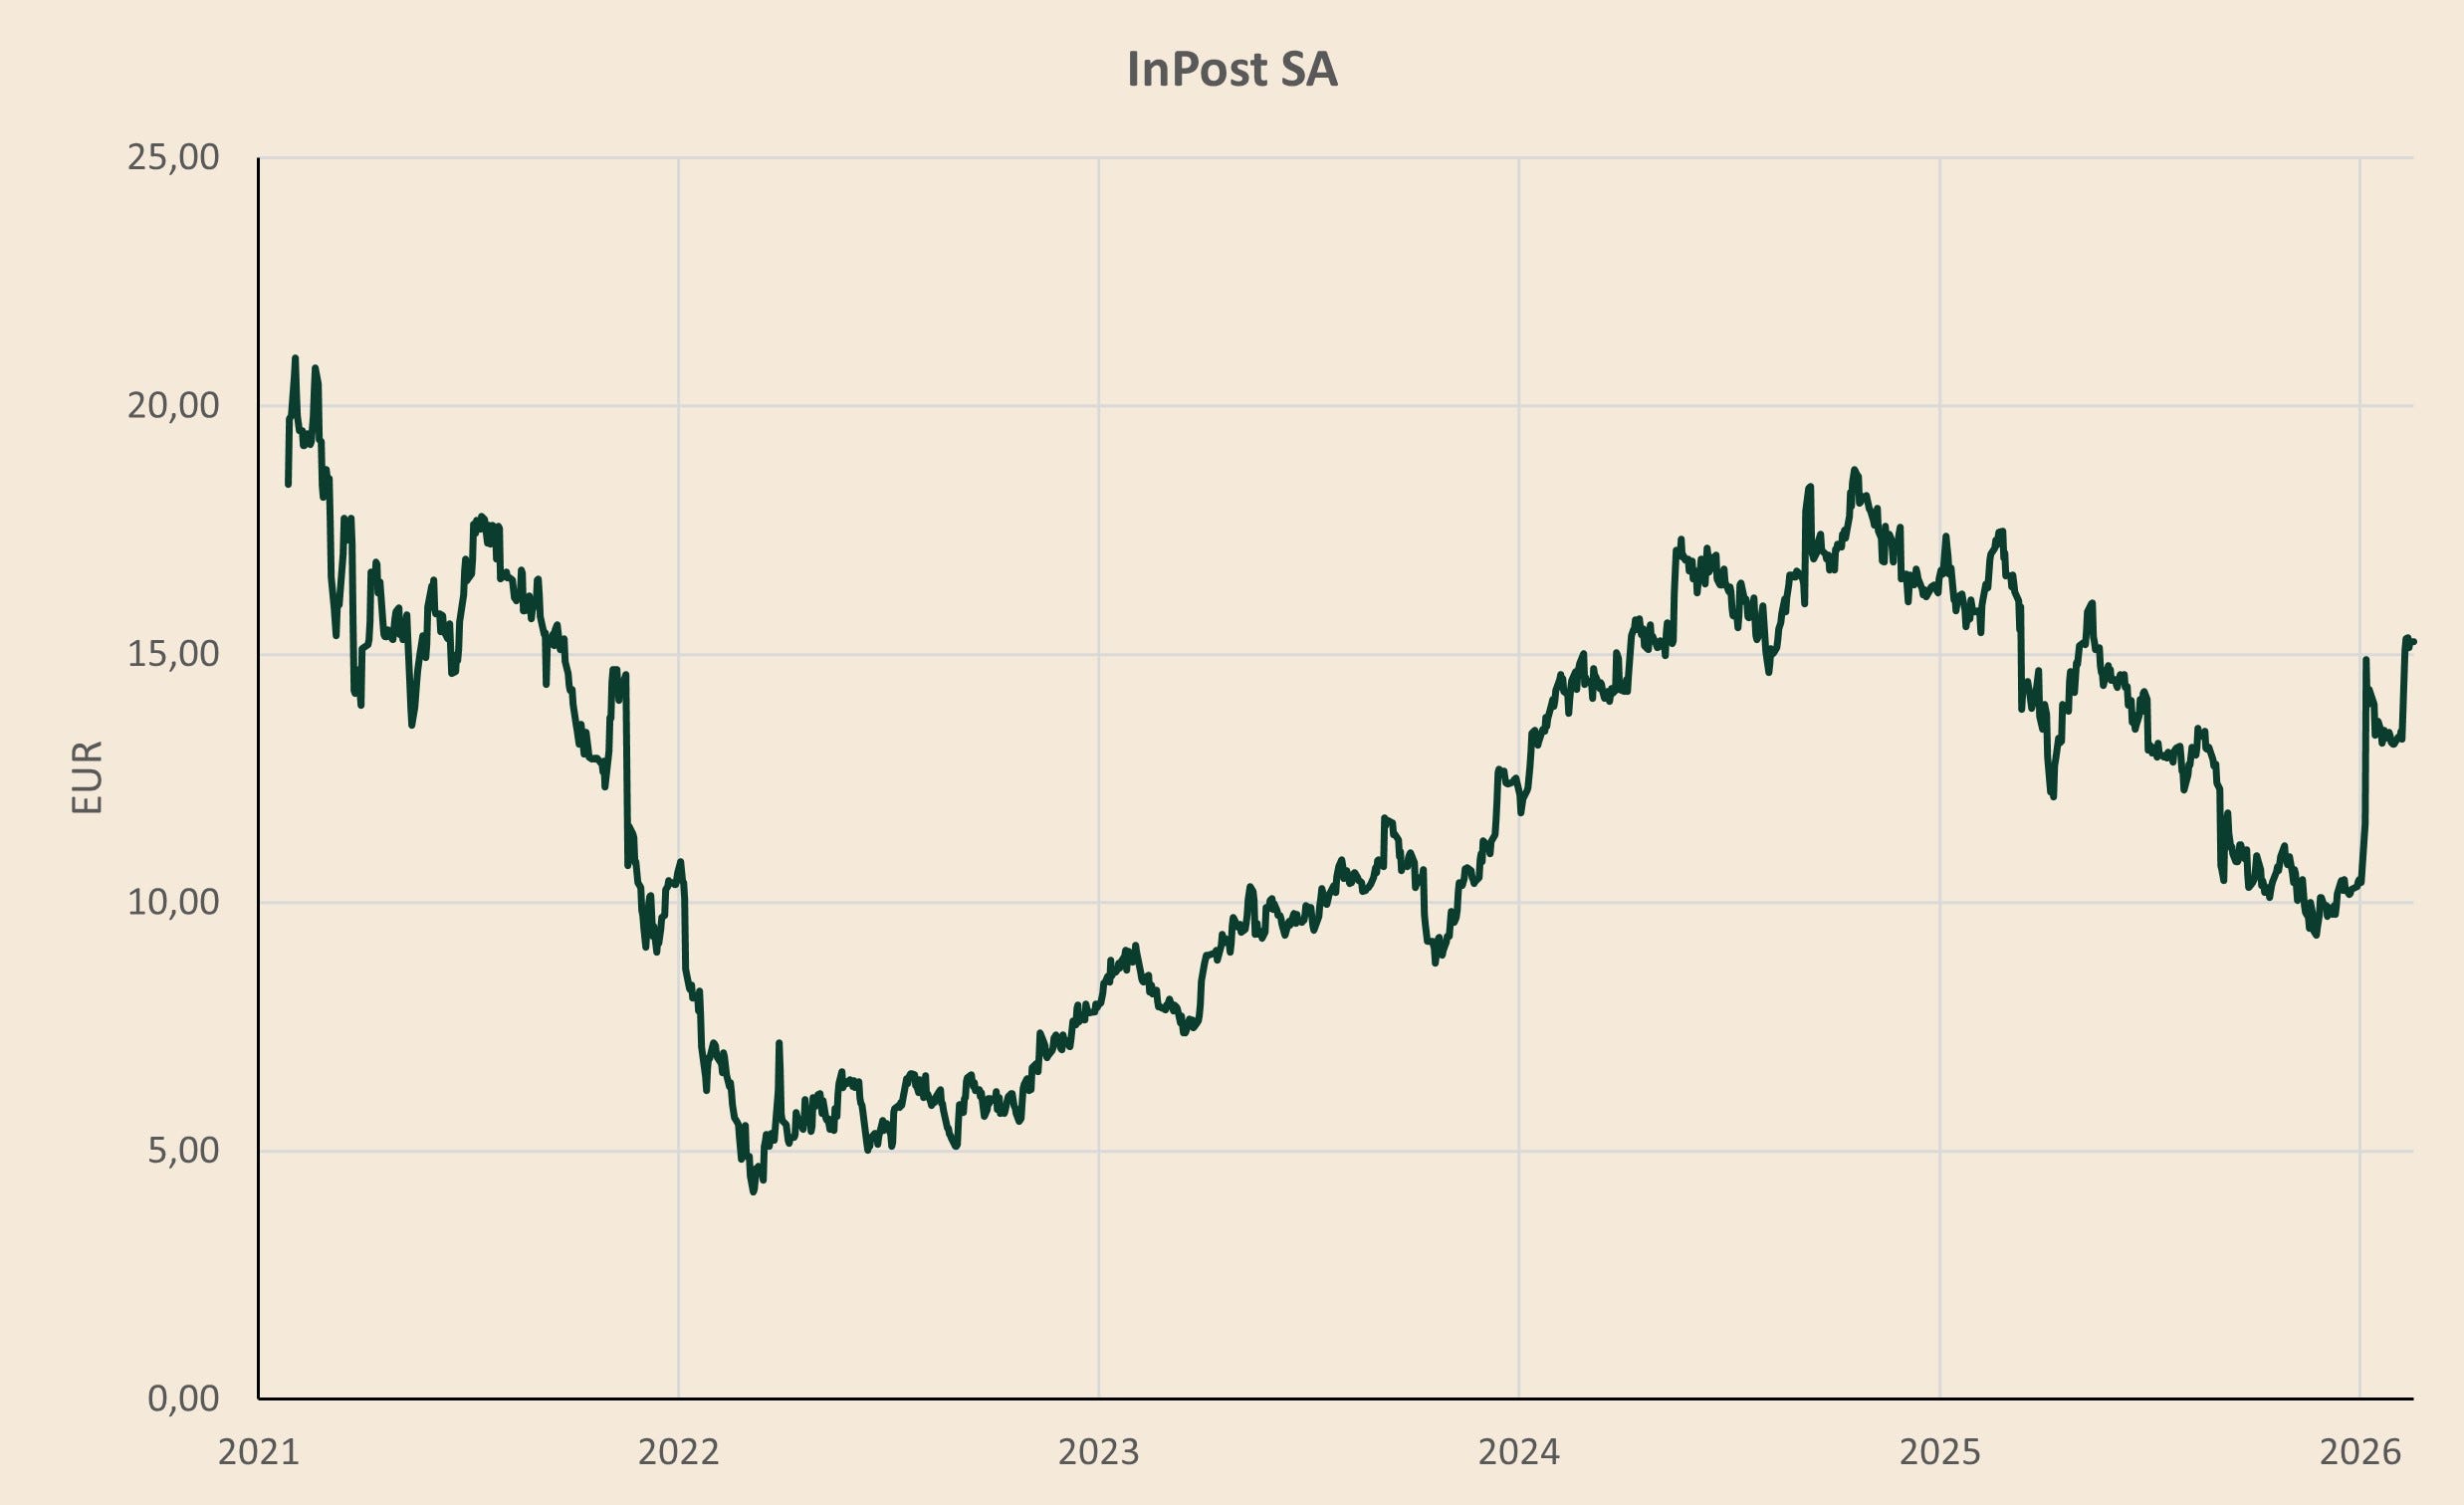
From mid-2022 through the end of 2024, the share price recovered and returned to IPO levels as InPost executed fundamentally. But toward the end of 2024, the narrative turned again because Allegro began scaling its own APM network more aggressively. This pushed the stock back below €8 by the end of 2025.
Allegro doesn’t face the same chicken-and-egg problem (as for a new entrant) because it is not an independent logistics provider; it can try to steer existing volume into its own logistics. To build out a network faster, Allegro partnered with competitors of InPost (DHL, DPD and Orlen) and integrated their APMs into its platform (somewhat comparable to Amazon Delivery).
As of Q3 2025, Allegro said it had surpassed 33k “APMs” in Poland—roughly 6k of which were Allegro-owned, with the rest coming from partners—plus ~37k PUDOs. On the surface, that sounds like Allegro built, in just 2–3 years, a network that took InPost nearly two decades to assemble.
But the headline counts are misleading. The raw number of “APMs” ignores a key dimension of network capacity: how many compartments each APM actually has. Allegro doesn’t disclose compartments per locker (maybe for exactly that reason…), but a quick Google search for “DPD locker Poland” gives you plenty of examples where the APM is a small unit with fewer than ~20 compartments—versus roughly ~143 compartments per APM on average for InPost. In other words, counting “APMs” without adjusting for size can massively overstate the real, usable capacity of the network.
However, while dependency on Allegro was very high in early 2021, the relationship today looks more balanced. InPost has become so dominant in Poland that it is hard for Allegro to shift meaningful volume without hurting the checkout experience (because customers want InPost as a delivery option).
In 2020, InPost generated 28% of revenue from Allegro Smart!, plus additional volumes flowing through Allegro where end customers pay for delivery (where Allegro has less influence on the carrier choice).
InPost has reduced that dependence: Revenue generated directly through Smart! had declined to 18% by the end of 2024, and internationally InPost grew with platforms such as Vinted, which have become key customers (Vinted represented ~23% of revenue in 2024). Within Poland, Allegro’s revenue share is still ~30%, relatively stable over the years. But from a group perspective, Allegro became less meaningful.
At an investor conference that I attended in September 2025, it was said that InPost handles 60% of Allegro’s volume (with 98% next-day delivery). Conversely, Allegro accounts for only 40% of InPost’s volume at the group level. As diversification increases, negotiating power tends to shift toward InPost.
6. Poland: what risks became visible — and why the market got nervous
The Polish success story is impressive: InPost now delivers roughly half of all parcels in the country, has extremely dense APM coverage (a large share of the population lives within walking distance of a locker), and a very high share in the OOH channel. Poland is a European leader in OOH. Still, three factors weighed on the narrative in recent years.
First, the fear of significant volume losses by large customers. Allegro’s announcement that it would build its own lockers aggressively was the immediate trigger for the post-IPO sell-off. Even if such a move is operationally difficult, the mere perception of potential volume loss is enough to compress multiples.
Second, the question of whether the APM moat is replicable. In Poland, there have been multiple attempts to attack InPost. The state-controlled energy group Orlen built its own locker network and offered prices far below InPost, but according to market commentary struggled with very low utilization — a signal that price alone does not reliably move customers and merchants. Even large international players (for example from the Alibaba / AliExpress ecosystem) have dialed back ambitions and restructured projects.
Third, typical macro and market-mechanics effects. The COVID parcel boom normalized, and the IPO valuation had been expensive. In those phases, markets tend to overreact — especially when story risk (Allegro) is highly visible.
7. International expansion: rolling out the Polish playbook in Western Europe
With Poland as a cash cow, InPost has resumed expansion into Western Europe — this time more focused and disciplined than earlier, less successful attempts in the 2010s. The logic is straightforward: in markets historically dominated by doorstep delivery (the UK) or PUDOs (France), a dense and well-run APM network can drive a similar shift as in Poland. A high PUDO share already suggests that customers are willing to use OOH solutions, making APM-adoption even more likely.
Internationalization expands InPost’s total addressable market materially. Today, InPost operates (besides Poland) in
the UK & Ireland,
Italy,
France,
Spain,
Belgium/Luxembourg,
the Netherlands,
Portugal.
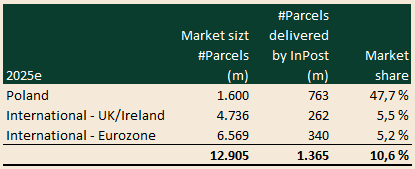
The latter are grouped in the “Eurozone” segment, where France the core market, followed by Italy, which has been growing very rapidly from a small base. Because InPost is still in a much earlier development stage outside Poland, market shares are far lower there at roughly ~5%, which leaves substantial room for growth, as these international markets combined are 7x larger than Poland in terms of annual parcel volume.
7.1 France
The key move in France was the acquisition of Mondial Relay in 2021. At the time, Mondial Relay was heavily PUDO-based (with a meaningful C2C component driven by platforms such as Vinted) and had little proprietary APM infrastructure. Since then, InPost has invested in an APM network and in operational performance. A simple cost logic explains why that can create value: PUDOs require per-parcel compensation to the shop operator, while APM delivery requires capex and a site return but is often cheaper per parcel. Even small savings per parcel can meaningfully shift margins in a high-volume business. At the same time, InPost is trying to establish next-day delivery as a differentiator — an area that is traditionally expensive in France and requires operational investment to scale.
In the Eurozone segment, InPost has already reached 19,310 APMs. During 2025, InPost deployed 6,867 APMs across these countries. That equals ~19 APMs being installed EVERY day. This demonstrates the underlying momentum in locker adoption across Western Europe.
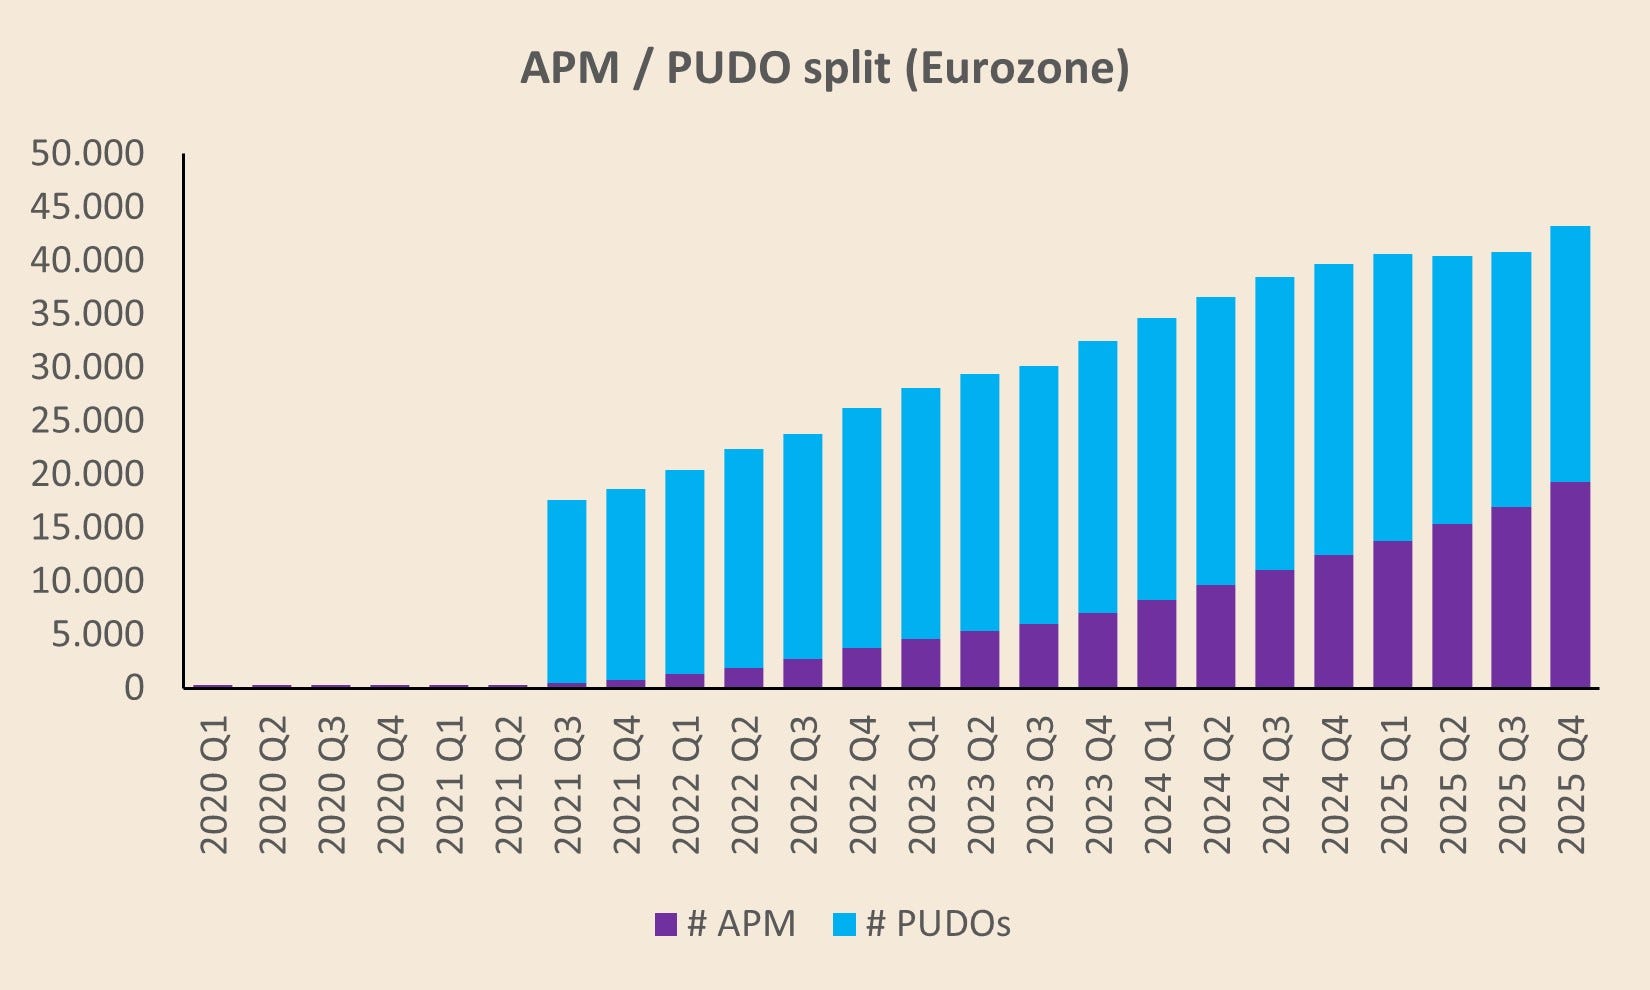
Early data points suggest customers adopt APMs quickly. A significant portion of Mondial Relay volumes is already being delivered via APMs, while the PUDO network remains an anchor for density. Competitors exist (for example, La Poste / DPD), but they face the same hurdles: access to great locations, utilization, service quality, and the question of whether OOH expansion cannibalizes profitable doorstep delivery.
Cannibalization is a real issue for incumbents. If you already have a high market share in 2Door delivery (for example DHL in Germany), you are forced to participate in an APM rollout when new competitors try to gain share — because you can’t afford to leave the channel to others. Incumbents have to invest heavily (high capex) without necessarily winning meaningful incremental volume.
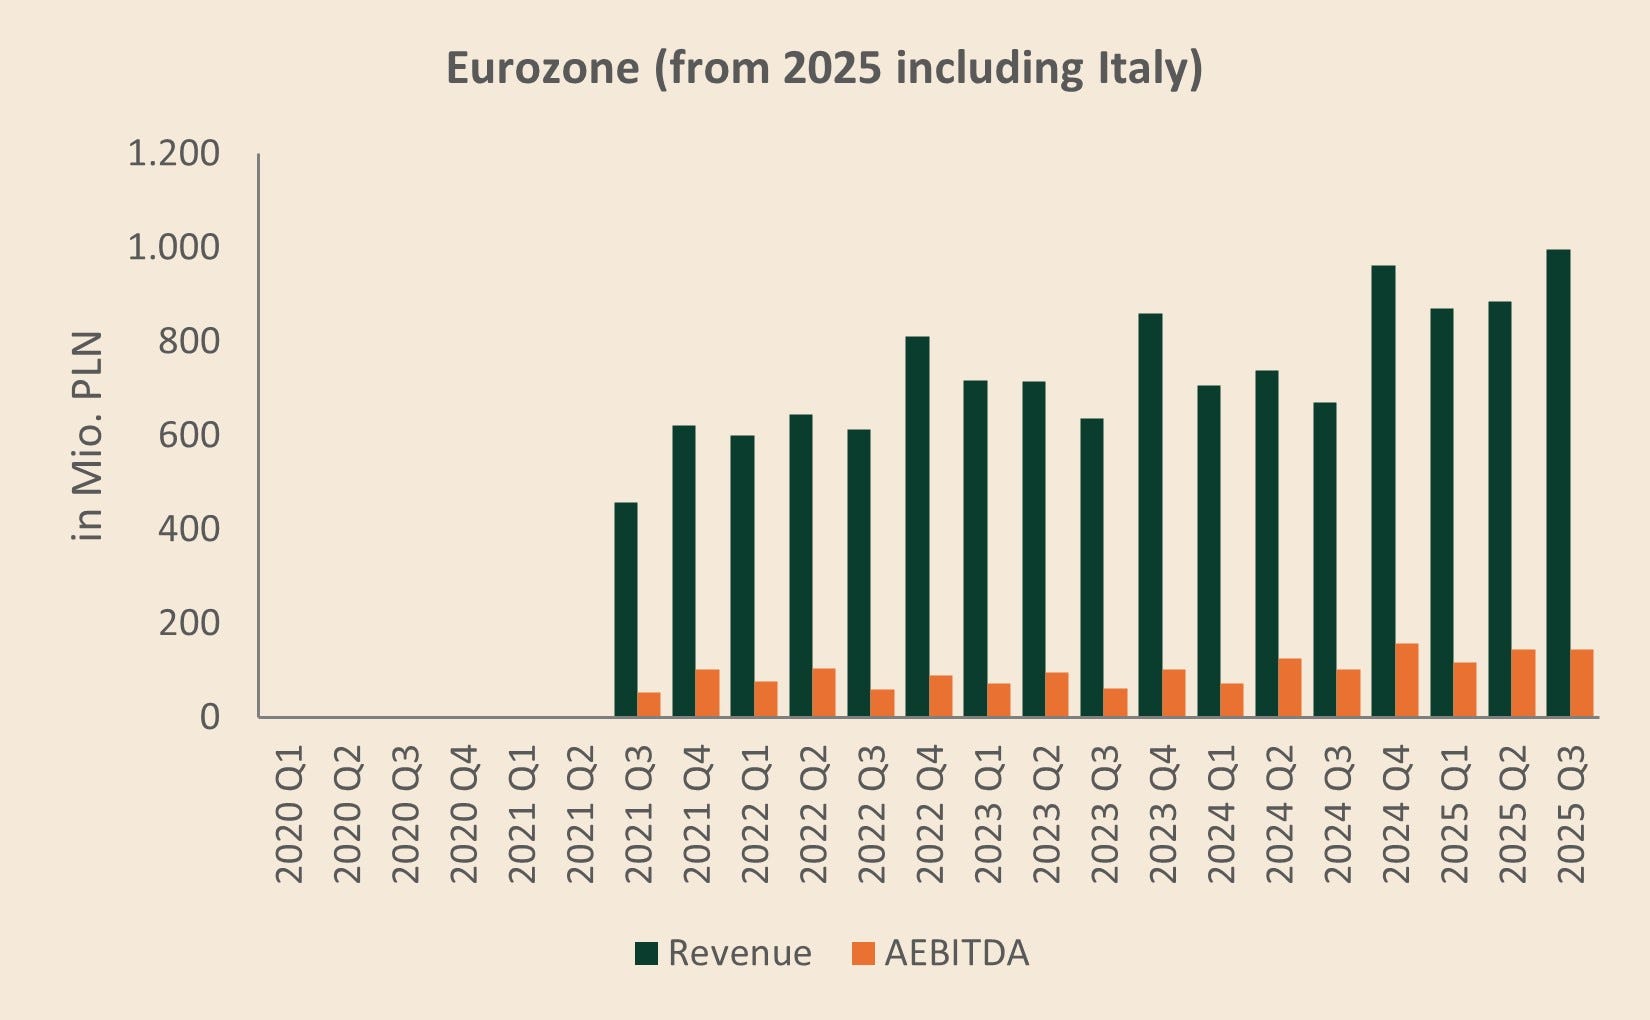
In the Eurozone, InPost grew ~30% year over year in 9M 2025, with an AEBITDA margin of ~15%.
7.2 UK: entering through returns and C2C, then moving toward B2C
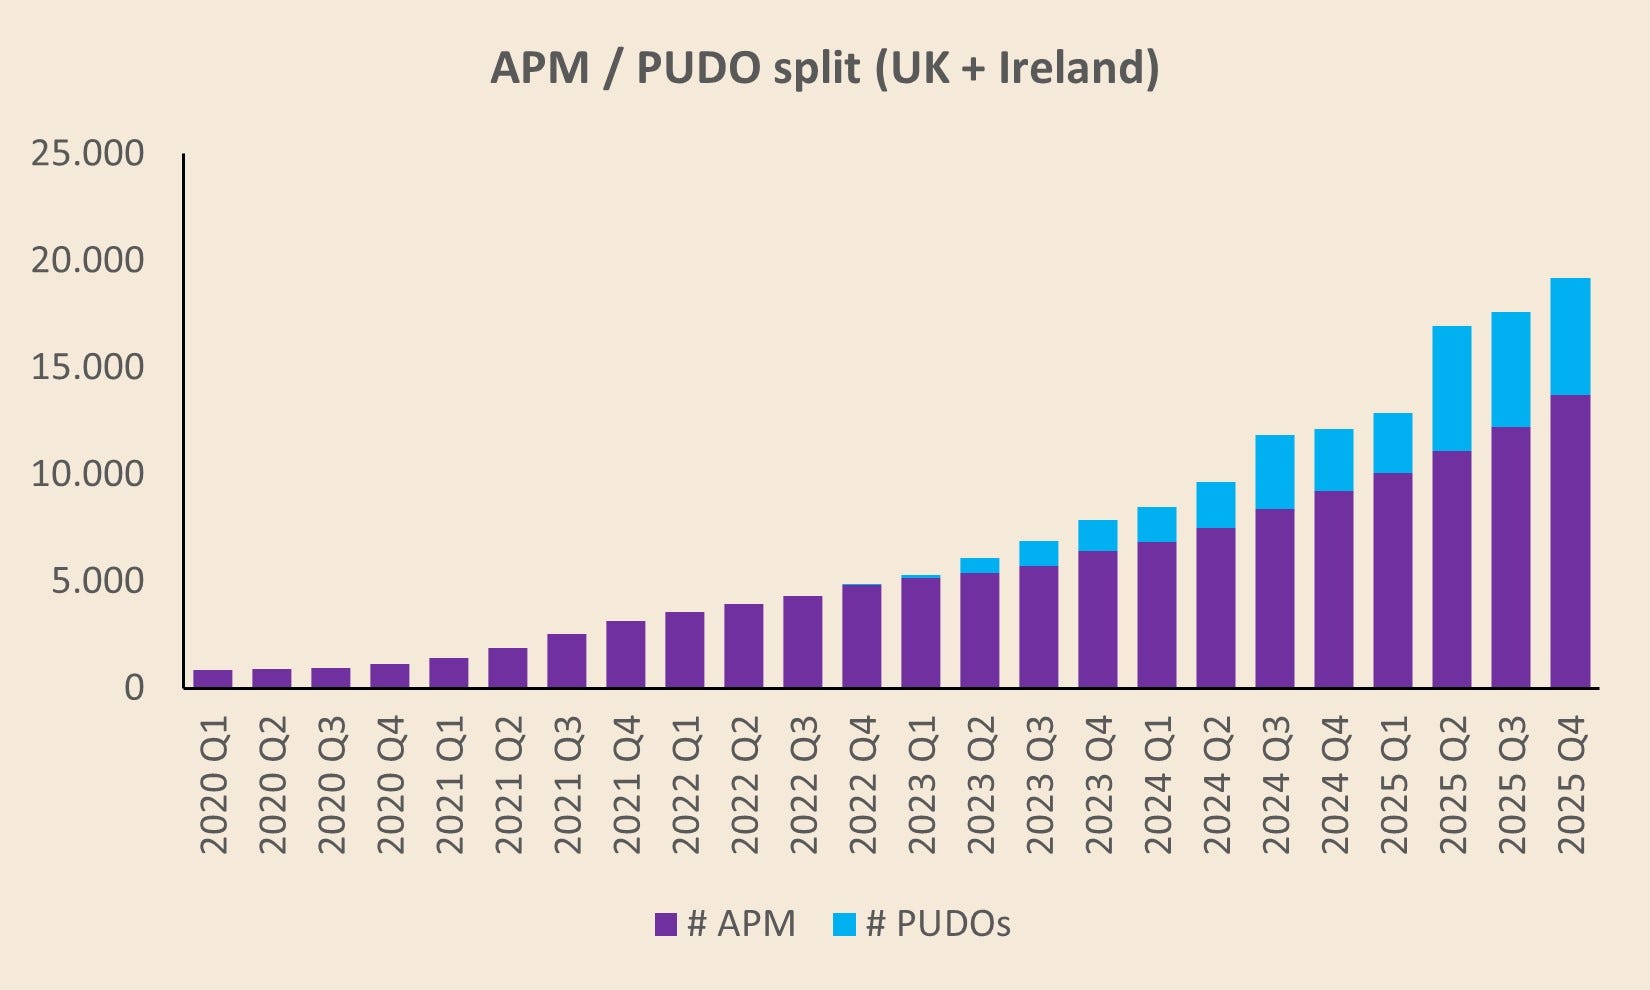
In the UK, InPost took a different route. Market entry began organically in 2017 via returns. That is smart, because the returns carrier is often chosen after the purchase and depends less on checkout integration — ideal for building brand awareness and driving network usage. In parallel, the C2C business grew (among other things driven by second-hand platforms such as Vinted). As utilization increased, unit economics improved; at times, utilization of the APM fleet even ran above 100%, which signals that demand and capacity are tightly linked in the build-out phase. In fairness, InPost also dealt with long dwell times: if customers leave parcels sitting in lockers for too long, utilization can hit 100% without the corresponding throughput behind it and that negatively affects growth and profitabtility (and hence ROIIC).
For a long time, a key bottleneck was backend logistics because partners could cap volumes. InPost initially operated only the APMs without the broader logistics infrastructure (depots, sorting hubs, couriers). This was addressed through the connection to, and later acquisition of, Menzies — a network with dense routes from the news-trade business that fits InPost’s needs surprisingly well. This gave InPost more control over capacity and service quality. The next step is B2C, which requires large-scale sorting and distribution centers — meaning capex — but that is also where the biggest value creation sits, because B2C volumes can lift utilization further.
InPost is still at a very early stage of market penetration in the UK, and it is likely that volumes will grow as APMs are installed and a larger share of the population is reached.
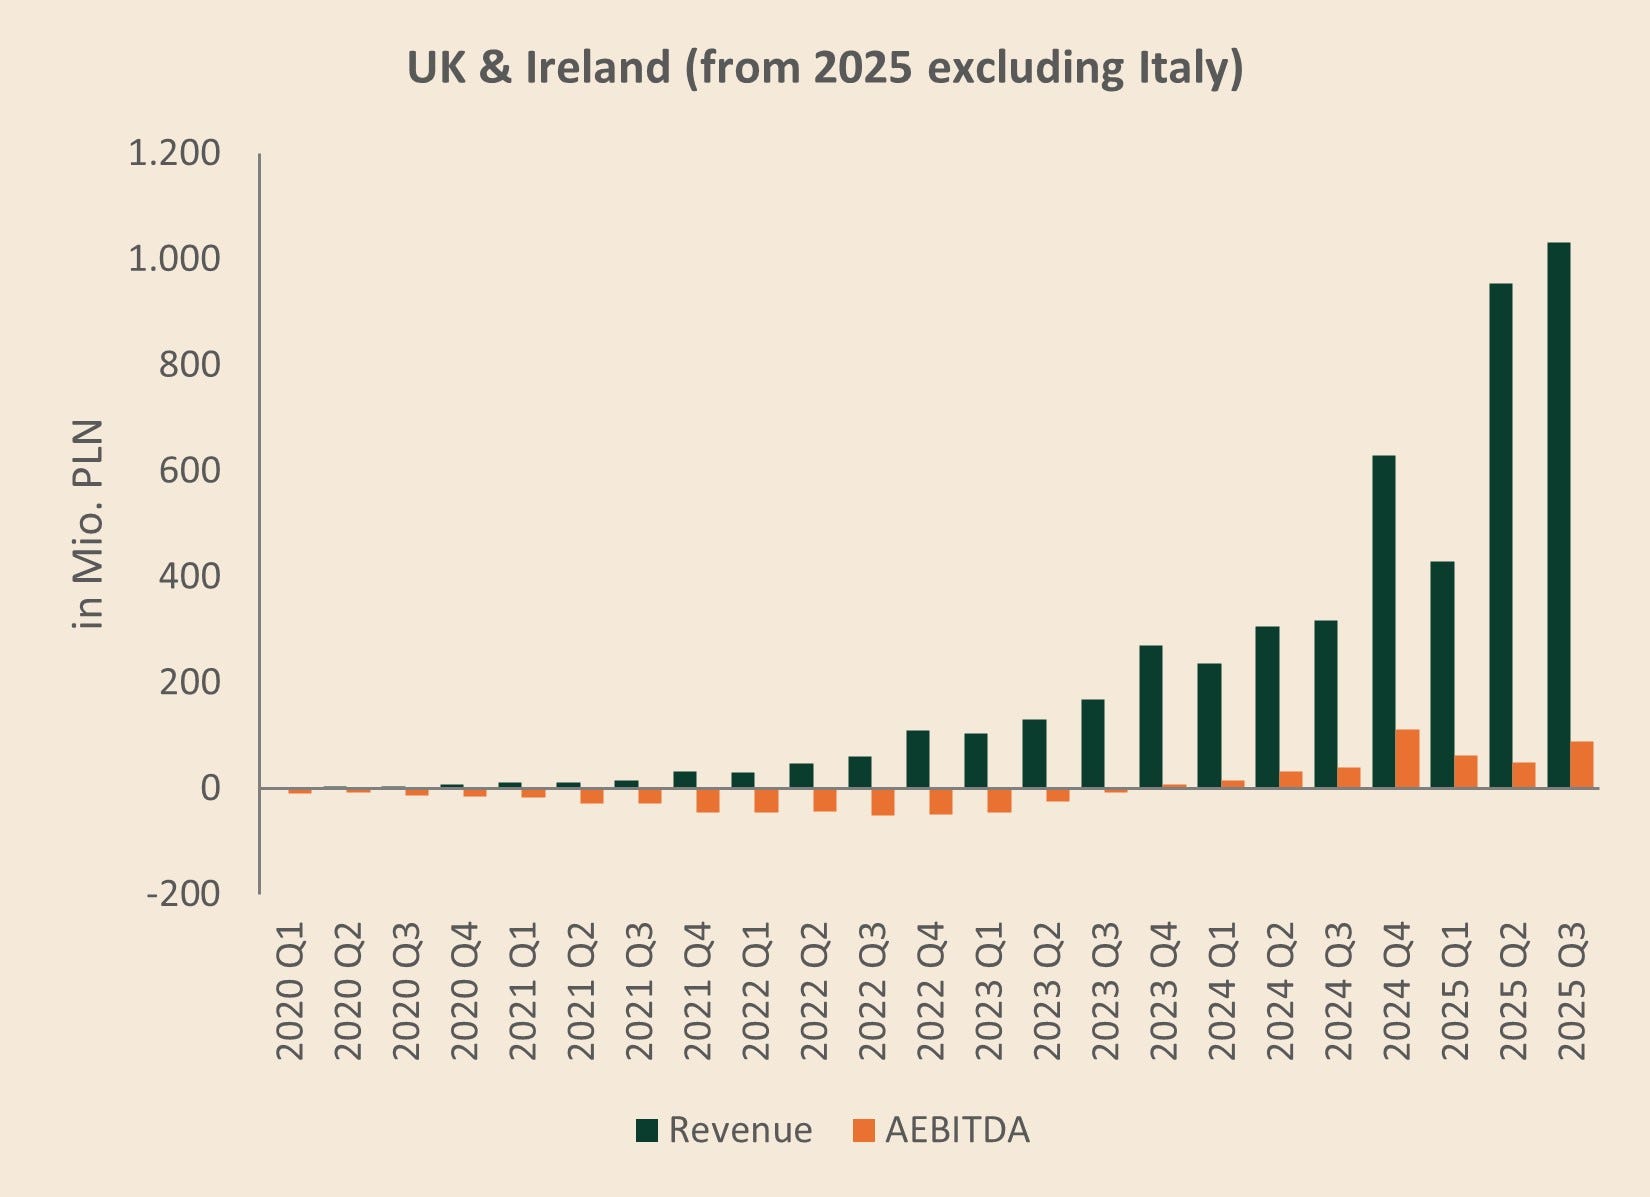
In 2025, InPost took another step to win volume and acquired Yodel (a 2Door carrier). This pressures margins in the short term, but comes with an instant 5% increase in market share and the possibility to scale margins through operational improvements. You can see this clearly in the chart below: starting in Q2 2025, revenue jumps while AEBITDA is burdened. The graphalso shows how quickly AEBITDA can be generated and scaled once volumes come in. In Q4 2024 (seasonally the strongest quarter due to black beek and christmas), InPost already achieved an AEBITDA margin of ~18% versus ~3% in Q4 2023.
8. Financials / Valuation
Financially, InPost is a major success: a highly profitable, mature but still growing core business in Poland, plus international expansion that currently carries lower margins but represents a much larger end-market option. Over recent years, InPost has shown exceptional growth: revenue CAGR was ~56% per year from 2017–2024, while EBITDA grew from PLN 18 million to an estimated ~PLN 4 billion in 2025 (despite temporary earnings pressure from the Yodel acquisition). Growth has been mostly organic, although the Mondial Relay acquisition (2021) was also an important driver. EBITDA margin rose from roughly ~4% to ~31%.
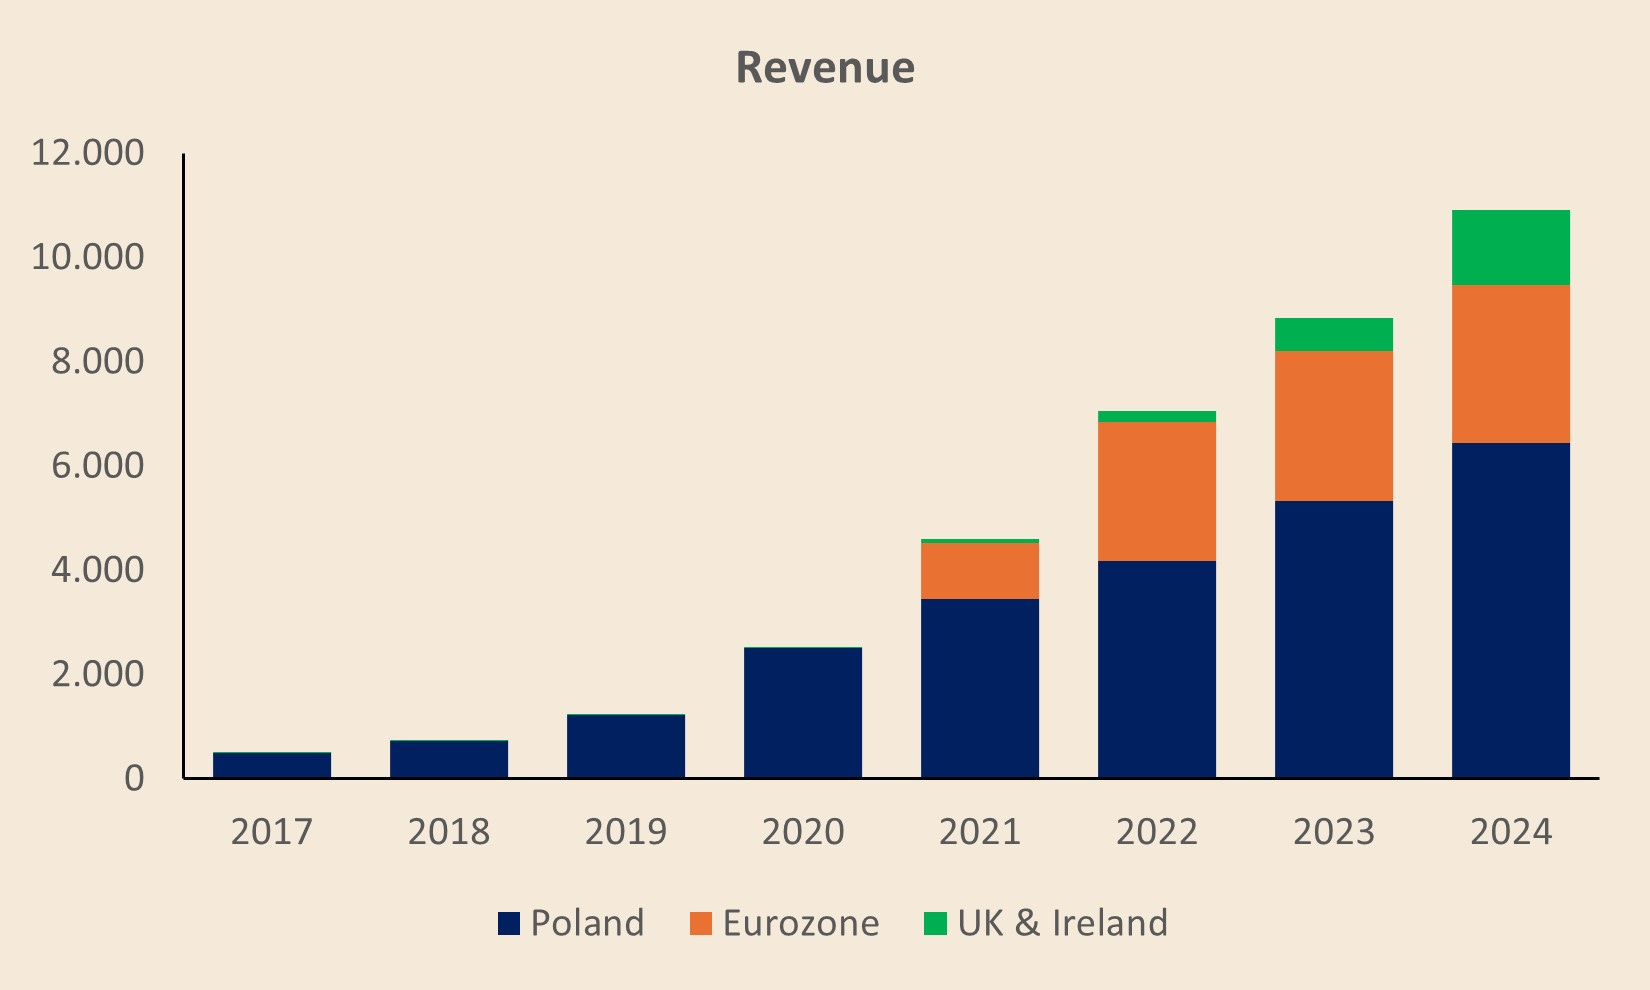
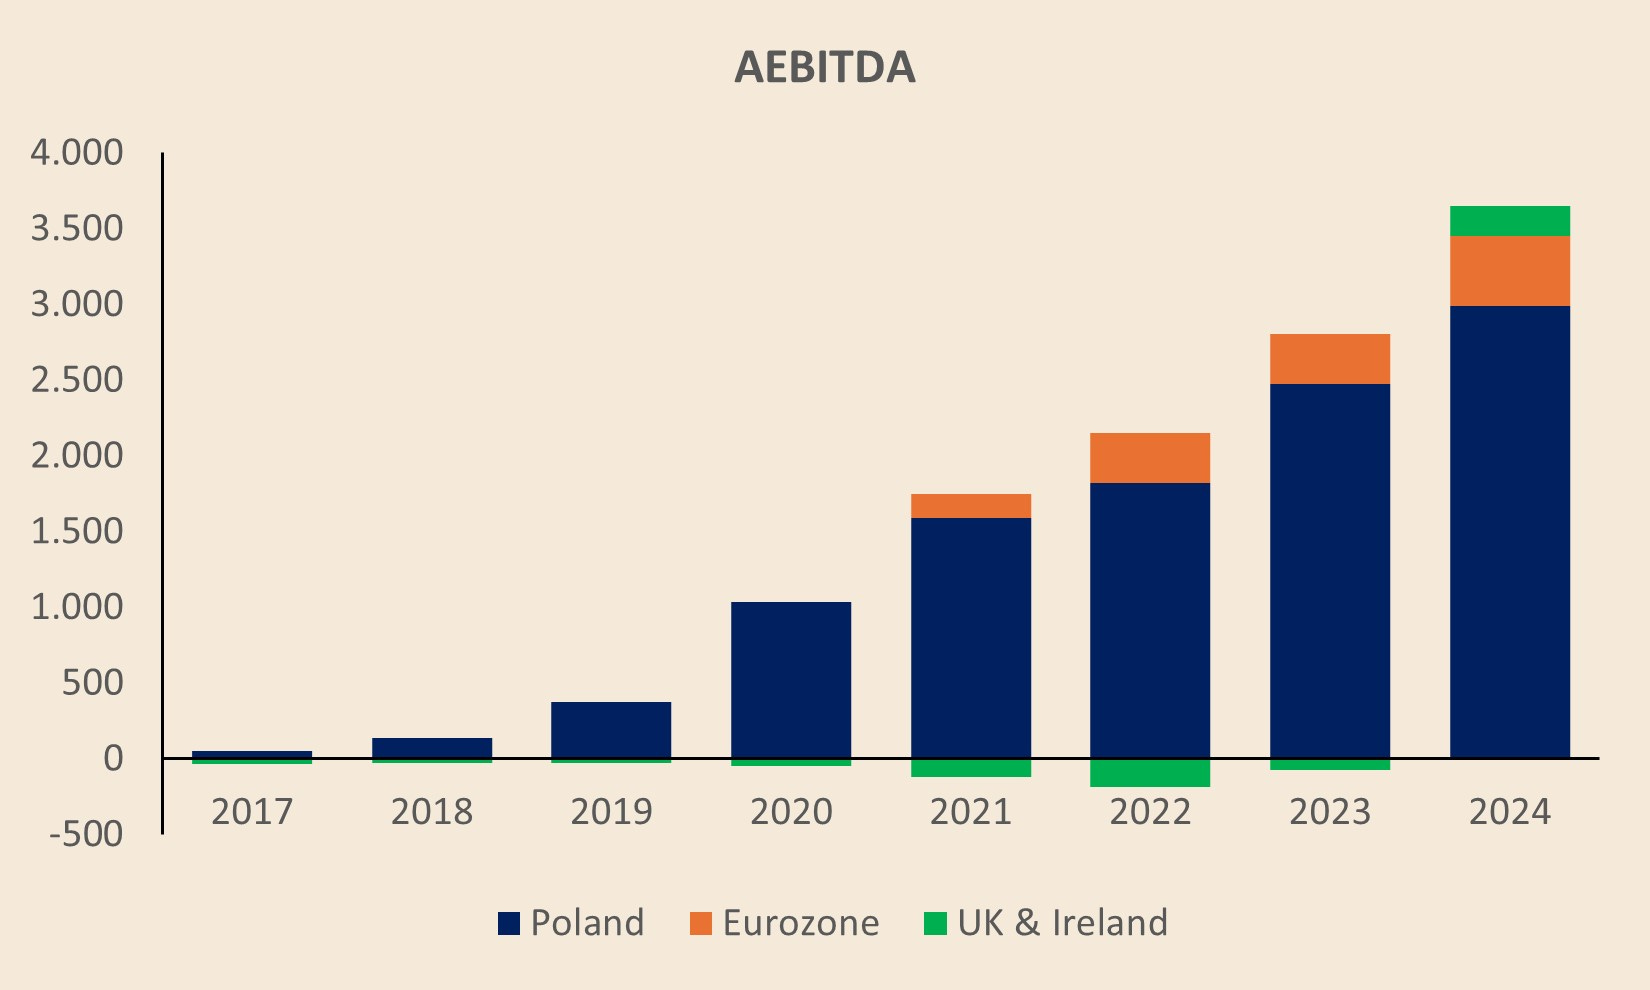
The Polish core business produced a pretax ROIC of >55% in 2024. I calculated that the reinvestment rate in Poland was ~66% over 2017–2024, with a ROICE of ~69% — an extremely attractive return profile explaining the significant earnings growth.
It is therefore easy to understand why InPost is trying to replicate the model in Western Europe.
Based on the closing price on Dec 31, 2025, InPost’s market cap was ~PLN 22 billion. With net debt of PLN 5 billion (Sep 30, 2025, excluding lease liabilities), enterprise value was ~PLN 27 billion. That implies an EV/EBITDA multiple of ~6x for 2026. As discussed above, Poland alone could likely generate ~PLN 3 billion of free cash flow today without additional growth capex. That would mean the stock traded at ~9x EV/FCF (Poland), or a ~11% yield — with the international business effectively free on top.
One could take this as evidence that the stock was far too cheap, given the quality of the business model, the moat, the returns on capital, the historical growth, and the remaining growth runway.
But…
9. The takeover offer
In early January 2026, initial reports about a potential takeover emerged, and the stock repriced immediately. InPost confirmed this on Jan 6, 2026, but did not disclose either the buyer or a potential price. With no anchor, the stock jumped to ~€15 and then fell back over the following days to ~€13.2.
On the same day, rumors surfaced that the PE-investor Advent was behind the offer.
In 2017, founder/CEO Rafał Brzoska entered an investor agreement with Advent International. The stated goal was to acquire 100% of the shares of Integer.pl / InPost and delist the group two years after the first IPO, stabilizing and rebuilding it outside public markets with additional equity capital; Brzoska remained a shareholder.
After the restructuring and significant operational build-out (including scaling the locker network), Advent brought InPost back to public markets during the e-commerce boom. The second IPO took place on Euronext Amsterdam on Jan 27, 2021 at an IPO price of €16 per share. Advent remained the dominant shareholder after listing (a large secondary sell-down at IPO, but still a meaningful remaining stake) and only reduced its position gradually in subsequent years. Before the IPO, Advent held ~83% while founder/CEO Brzoska held 12.2% via his holding company (A&R).
Out of ~500 million shares outstanding, 175 million were placed at IPO, most of which came from Advent (168 million).
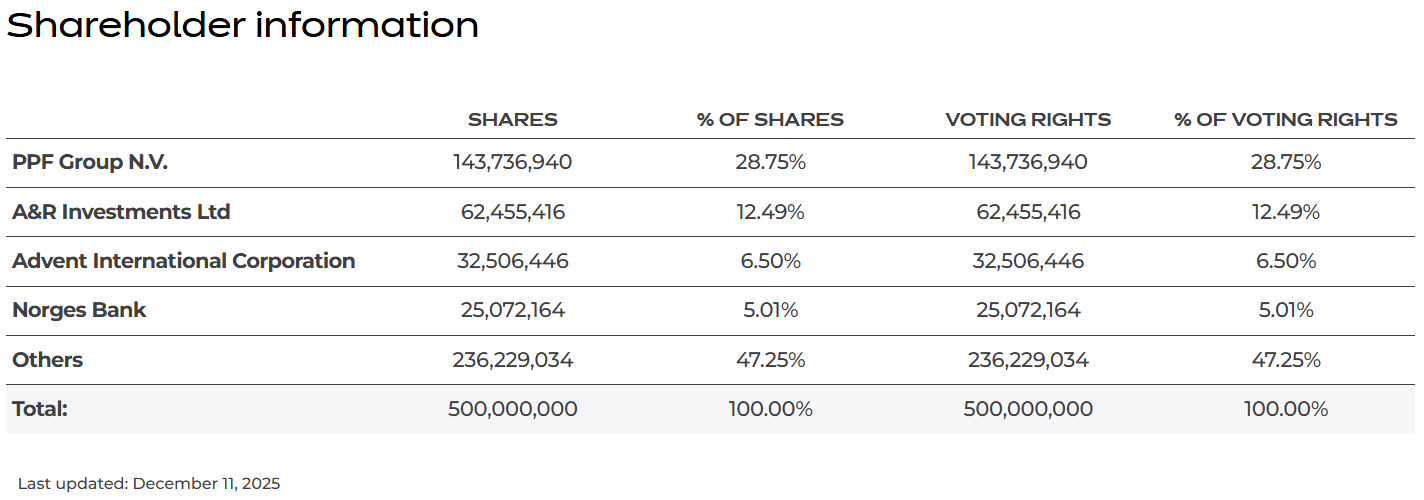
After the IPO, Advent continued to sell down and most recently reduced its stake to ~6.5%. The largest shareholder is PPF, a Czech investment group.
Then came the big bang on Feb 9, 2026.
A consortium of FedEx, Advent, A&R, and PPF made a recommended all-cash offer of €15.60 per share, valuing InPost at roughly €7.8 billion. Formally, the offer is marketed as an “attractive premium” (including +50% to the “undisturbed” price on Jan 2, 2026). At the same time — and this is the crux of the criticism — it does not even take the stock above the IPO price from 2021: InPost listed at €16 per share, and the offer is below that.
With the deal, the power balance shifts once again — and that is what bothers many shareholders. After completion, Advent and FedEx are each expected to hold 37%, A&R (Brzoska) 16%, and PPF 10%. In other words, the founder/CEO increases his stake meaningfully without any further capital deployment (as was confirmed in the Merger Analyst Call) while minority investors are being cashed out at €15.60 (if the deal closes).
This is a raid on long-term minority shareholders, and the fact that the CEO supports it makes it feel even more one-sided. It’s pathetic that an opportunistic take-private, driven by the largest shareholders (currently ~48% combined) plus FedEx, succeed off a price that looks materially below what the business has delivered since the IPO.
InPost has executed strongly since the 2021 IPO. In 2020 (the year before listing), InPost generated PLN 984 million of EBITDA, almost entirely from Poland. The UK was negligible and dependence on Allegro was high. Today, just five years later, InPost generated an estimated ~PLN 4 billion of EBITDA in 2025. Dependence on Allegro is lower, and the TAM is 7x larger thanks to Western European expansion and after roughly ~€2.6 billion of incremental capital deployed since 2019.
After roughly ~300% EBITDA growth versus IPO, the company is supposedly worth less? That’s a complete rip-off.
And when the CEO is part of the buyer consortium and increases his stake without investing fresh capital, it doesn’t feel like a neutral process for minority shareholders — even if everything is formally within the rules.
The people with the best information and influence lock in the long-term upside; everyone else is paid out at what feels like a “joke” price. And they frame it as a “50% premium” to the pre-offer price—even though the stock had already fallen about 50% since October 2024.
The offer is recommended and supported by the Board. Closing is targeted for H2 2026 and depends, among other things, on acceptance thresholds and regulatory approvals. For shareholders, InPost is no longer primarily a fundamentals thesis; it becomes a deal decision: cash now versus the risk/optionality of a bump or a failed transaction.
Shareholders can bet on a takeover poker game and hope for a higher price. But who is realistically going to show up as a competing buyer on short notice? DHL? Amazon?
If you’re not invested, I would not initiate a position here: the upside to €15.60 is limited, while the downside is meaningful if the transaction fails and the stock reverts toward the pre-offer level. The only real “bull case” is betting on a higher bid, which is speculation, not compounding. Who is realistically going to show up NOW to acquire this high-quality asset as a competing buyer on short notice? DHL? Amazon? Maybe, but I doubt it.
If you’re already invested, it’s a tough call. You can sell now and redeploy elsewhere, which buys peace of mind and avoids having dead capital tied up for the next 6–9 months. You can hold and tender into the offer, but that likely means sitting on a largely capped outcome for months. Or you can hold out for another buyer to step in, but that’s a pure poker game—and the downside remains real if acceptance thresholds aren’t met or the deal breaks.
Personally, my path is to sell, reallocate to Teqnion, Röko, Topicus and Constellatoin Software, and keep watching the situation from the sidelines.
10. My learnings: great businesses aren’t enough — ownership can destroy everything
I take one clear lesson from this: even the best business model does not protect you if the ownership structure allows an opportunistic take-private at any time. Going forward, that means I will try to avoid private equity as a co-shareholder whenever possible. With large blockholders, I will ask more aggressively who has exit pressure, who controls the process, and who gets a seat at the table when things get serious — and who doesn’t.
I'm also quite disappointed in the InPost deal.
I recently faced a similar situation with another stock, Inforich, also being bought out by private equity.
I decided to sell out and redeploy the capital. As you say, why speculate on a higher offer?